

Almost nothing in my 35 years of writing about business, economics, investing and personal finance has hurt more people than the inflationary surge of a few years ago. Now, a sequel looms.
In no way am I forecasting a return to the 8.1 per cent inflation rate of June 2022. But the oil price rise of the past week is already costing us more to gas up a vehicle. A sustained increase will trickle down to many other goods and services we buy, notably food. Renewed inflation would also limit potential for an interest rate cut if the economy weakened, and disrupt financial markets.
Inflation 2.0 is a sequel you’ll hate - if it happens.
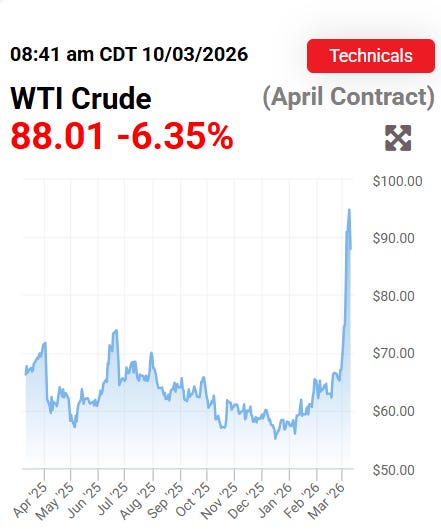
I write this after a recent drive past an Ottawa gas station where the price per litre was $1.55, compared to the $1.25 to $1.30 range in preceding weeks. Oil prices have come down from their peak of earlier this week, but are still about 34 per cent higher than year-ago levels. The only way this higher fuel cost doesn’t get passed along to consumers is if the Iran war ends quickly and cleanly. Who sees that happening?
The reason why inflation is so awful is that there’s really no protection for your day-to-day finances. The only defence is awareness - you weigh all current and future financial commitments against the likelihood that living your life will use up more of your take-home pay. There are already reasons for taking a cautious approach to your finances, trade war uncertainty and weak economic growth foremost among them. Now, you have another.
Cash is king in uncertain times like these and here’s where I’m keeping mine:
-Savven Financial: Offers 2.85 per cent rate as of March 10.
-Oaken Financial: 2.8 per cent
-EQ Bank’s 10-day notice account: Offers an interest rate of 2.35 per cent and requires 10 days notice to make a withdrawal. You can get 2.75 per cent if you’re willing to give 30 days notice for a withdrawal.
I am trying to set up an account at Canadian Tire Bank to take advantage of its 2.4 per cent rate, but it’s taking a while. I will report back on how well these accounts work in the near future.
The prospect of having to fight off renewed inflation is exhausting because we’re still adjusting to Inflation 1.0. The headline inflation rate has settled down to the low 2 per cent range, which is more or less normal by the standards of the past 20 years. But food inflation remains a massive problem. In January, Statistics Canada reported a 7.3 per cent inflation rate for food on a year-over-year basis and a 2.3 per cent overall rate.
Processing and shipment of food requires energy. So brace for some higher costs for food unless oil prices quickly retreat.
Storylines
OAS reform: Check out this LinkedIn thread to see why the inevitable re-boot of Old Age Security is going to be a slog for the federal government. A high earner complains about the OAS Recovery Tax, wherein affluent people have some or all of their benefits clawed back. OAS is excessively costly and will only get more expensive as the population ages. One solution is to make the OAS clawback more aggressive, while topping up benefits for low-income seniors via the Guaranteed Income Supplement.
Groceries: A discussion on how changing your shopping habits can help with soaring food costs. Buy in small batches, rather than one big weekly grocery binge.
Home prices: Good news for young people who feel priced out - a big bank economist sees affordability improvements in Ontario and B.C. Overall, the average home price costs 20 per cent or so less than it did at the peak a few years ago.
Chartage
A one-year view of oil prices from OilPrice.com. Time to check out GasBuddy.
Tune in
The two surviving members of The Doors, John Densmore and Robby Krieger, team up with the Nelson brothers, Micah and Lukas, plus a big roster of global musicians (Brazil, Cuba, Senegal, Spain) for a darn fine version of Riders on the Storm.
Good column today Rob. Many thanks. Also, I thoroughly enjoyed the version of “Riders on the Storm.”